GST on Plots: Where the Line Actually Falls
Schedule III of the CGST Act lists activities that are neither a supply of goods nor a supply of services. One entry reads, in part, sale of land. Three words, and they are the reason a plot purchase carries no GST — while several line items sitting beside it on the same cost sheet do.
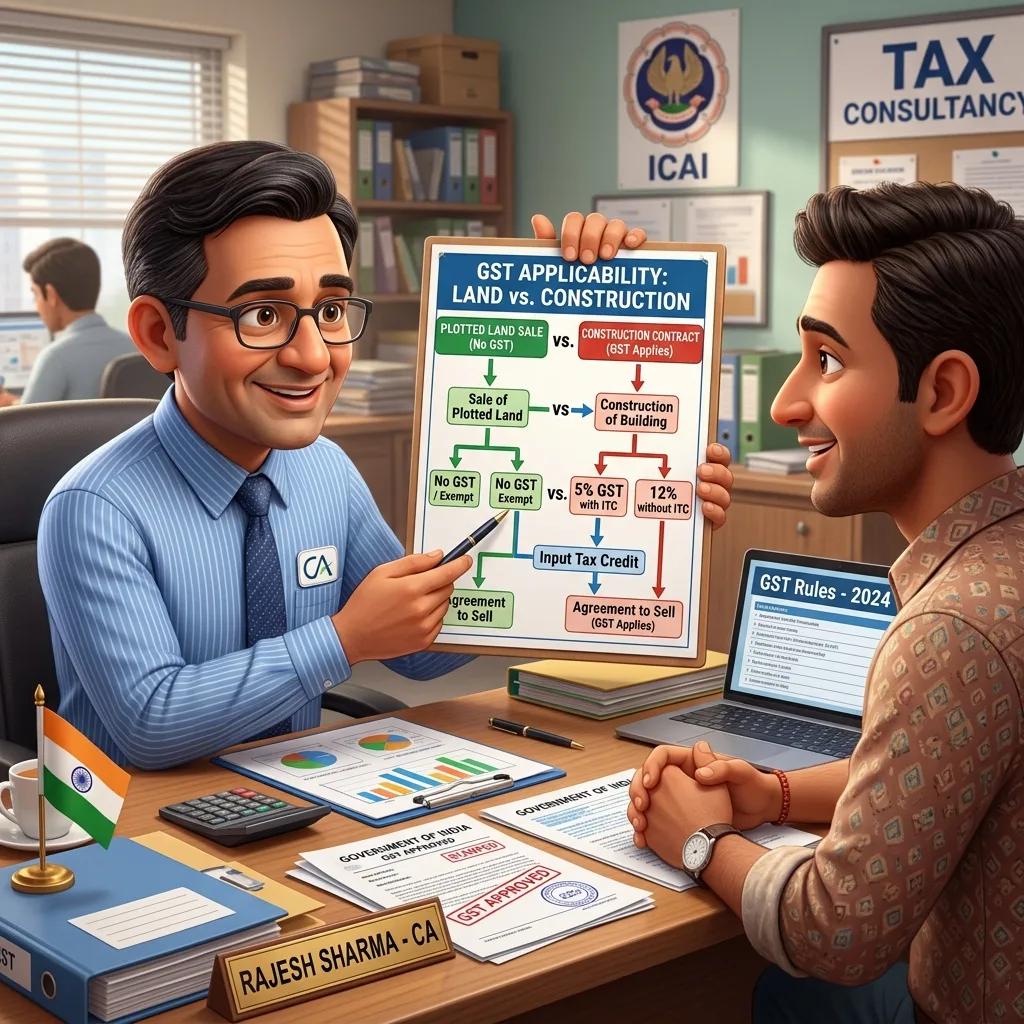
Schedule III of the Central Goods and Services Tax Act lists activities that are treated as neither a supply of goods nor a supply of services. One entry in that schedule covers, in part, the sale of land.
Three words, and they settle the question most plot buyers are anxious about. A transaction that is the sale of land is outside GST altogether. Not exempt, not zero-rated — outside the charge. But several items sitting beside the plot price on the same cost sheet are firmly inside it, and telling the two apart is worth the fifteen minutes it takes.
The Constitution put land in a different box
The exclusion is not an oversight or a concession. It follows from how taxing powers are divided in India.
Land and buildings are the subject of state taxation. Stamp duty on conveyance, registration fees, property tax — these belong to the states and predate GST by more than a century. When the GST regime consolidated indirect taxes in 2017, it deliberately did not annex land transactions, because doing so would have collided with a constitutional allocation and produced double taxation on the same transfer.
So the design is coherent. The state taxes the transfer of immovable property through stamp duty. The Centre and the states jointly tax the supply of goods and services through GST. A plot conveyance is a transfer of immovable property, and it pays the first, not the second.
What you will pay on your plot purchase, therefore, is stamp duty and registration at prevailing Telangana rates — the mechanics of which we set out in the stamp duty and registration guide. What you will not pay is GST on the land component.
The developed-plot question took years to settle
For several years after GST arrived, this clean rule ran into a practical complication, and it is worth understanding because it still generates confused advice.
A plot in a modern layout is not raw land. Before it is sold, the developer has laid roads, put in drainage, trenched water and electricity lines, built a compound wall, planted avenues and provided open spaces. Some tax officers argued that this activity amounted to a supply of services bundled with the land, and that the service component should attract GST.
Developers argued the opposite: that what is ultimately conveyed to the buyer is a plot of land, and that internal development is what makes it a saleable plot rather than a separate service supplied to the buyer. Advance rulings went in different directions across states, which is the least useful outcome a tax system can produce.
The position was subsequently clarified by the Central Board of Indirect Taxes and Customs, which confirmed that the sale of land after such development — levelling, laying drainage lines, water lines, electricity lines and similar works — remains sale of land for these purposes and falls under the Schedule III entry. The clarification aligned the treatment of developed plots with the treatment of raw land.
That is the settled position at the time of writing. It is also precisely the sort of position that gets revisited, refined or litigated, which is why the sensible reader treats this article as orientation and a chartered accountant as authority.
Where GST genuinely applies around a plot purchase
The land is outside. Several things adjacent to it are not, and a buyer who assumes "no GST on plots" means "no GST anywhere in this file" gets a surprise.
Construction services. The moment you engage a builder or contractor to construct a house on your plot, you are buying a service. That contract attracts GST at the applicable rate for works contracts and construction services. This is usually the single largest tax item in the whole plot-to-villa journey, and it belongs in your construction budget from the first spreadsheet rather than being discovered at the first running bill.
Professional and brokerage fees. Architect fees, structural consultancy, project management, legal fees and brokerage are all services. Registered service providers charge GST on them.
Materials, where you buy them directly. If you procure cement, steel, tiles or fittings yourself rather than through a turnkey contractor, those purchases carry GST at their own rates. Whether that works out cheaper than a composite contract depends on the numbers in front of you.
Certain amenity and membership charges. Where a developer or association levies a charge that is genuinely a service rather than part of the land consideration, GST can apply. The characterisation matters, and it should be visible on the invoice rather than buried in a lump sum.
Under-construction flats are the contrast that makes the rule visible
The clearest way to see the boundary is to look at what happens on the other side of it.
Buy an under-construction apartment and you are, in GST terms, buying construction services from the developer, because the building does not yet exist as completed immovable property. GST applies. Buy a finished flat after the developer has received its completion or occupancy certificate, and the transaction is a transfer of immovable property. GST does not apply.
The rates and the input tax credit treatment for under-construction residential property were restructured some years into the regime, and they differ between affordable and other housing. Rates change; look up the current position on the official CBIC site or ask your accountant rather than trusting any article, including this one, on the specific percentage.
The structural point survives every rate revision. GST follows the supply of a service, and the point at which a building stops being a service and becomes property is the completion certificate. Land never enters that sequence at all.
Read your cost sheet like an auditor
The practical skill this article is really about is reading a developer's cost sheet and knowing which lines should carry tax.
Ask for the price to be broken out. The consideration for the plot itself is one line and should carry no GST. Anything described as development charges, infrastructure charges, amenity charges, club charges, corpus or maintenance advance is a different matter, and the correct treatment depends on what the charge actually is rather than what it is called. A charge that forms part of the consideration for the land is treated with the land. A charge for a distinct service is a service.
If GST appears on a line, three questions follow. What supply is being taxed? At what rate, and under what classification? And is the supplier's GSTIN printed on the invoice, so the charge is going where it is supposed to go? A tax collected on a document without a GSTIN is not a tax. It is a payment to somebody.
Then keep every invoice. If you later sell, your cost of acquisition and improvement matters for the capital gains computation, and GST paid on construction forms part of what you actually spent. We deal with that side of the ledger in capital gains on land, and with the deductions available against a house in tax benefits on property.
What this looks like on an actual plot purchase
Take an HMDA-approved plotted layout of the kind we develop. At Sanctuary, a buyer acquires a plot in a 45-acre layout with underground water, electricity and drainage, roads, footpaths, rainwater harvesting and a compound wall already in place, at a price starting from ₹45 lakh.
That consideration is for land. Stamp duty and registration apply to it at prevailing state rates. GST does not.
If the same buyer then engages a contractor to build a villa, the construction contract is a service and carries GST. The plot's tax position and the house's tax position are separate events with separate treatments, separated by the buyer's own decision about when to build. This is one of the quieter advantages of the plotted format over an under-construction apartment: the tax on construction arrives when you choose to trigger it, rather than as part of the entry ticket.
Input tax credit is where the developer's economics sit, and it reaches you indirectly
One mechanism deserves explanation because it shapes prices you pay without ever appearing on your invoice.
GST is designed to tax value addition. A business that pays GST on its inputs — cement, steel, contractor services, professional fees — can ordinarily set that against the GST it charges on its outputs. That is input tax credit, and it is what stops tax cascading through a supply chain.
When an output is outside GST altogether, as the sale of land is, the credit chain breaks. The developer still pays GST on inputs. There is no output tax to set it against. That embedded cost does not disappear; it becomes part of the developer's cost base and is recovered in the price of the land like any other cost.
This is not a scandal and it is not avoidable within the current design. It is worth understanding for one reason: it explains why "no GST on plots" does not mean "no tax anywhere in this price". Tax is in the price. It is simply not a line item you can see, question or claim.
The same logic operates in the construction sector's rate structure, where lower output rates were paired with the withdrawal of input tax credit. Whenever you see a low headline rate in this industry, ask what happened to the credit, because the two move together.
TDS on property is a separate obligation and it catches buyers out
This one is not GST at all, and it belongs here because buyers routinely conflate every tax in a property transaction.
Under the income tax provisions applicable to transfers of immovable property other than agricultural land, the buyer is required to deduct tax at source on the consideration where it exceeds a prescribed threshold, deposit it with the government, and furnish the relevant challan and certificate. The obligation sits on the buyer, not the seller.
Two consequences follow, and both bite. If you fail to deduct, the liability and any interest or penalty is yours, not the seller's. And the seller will want the deduction reflected correctly against their PAN, so getting the paperwork right is part of closing rather than an afterthought.
Rates and thresholds are revised from time to time, and the treatment differs where the seller is a non-resident, which is a materially different and more demanding compliance path. If either side of your transaction involves a non-resident, take specific advice before the money moves rather than after.
Questions worth asking before you sign
Is any part of the consideration described as something other than the price of land, and if so, what exactly is it for?
Does the agreement separate the land consideration from any development, amenity or membership charge, and is that separation carried through to the invoices rather than living only in the conversation?
If GST is charged on any line, what is the classification and the rate, and does the supplier's GSTIN appear on the document?
If construction is being offered as part of the same transaction — a plot-plus-construction package — how is the contract structured, and what does that structure do to the GST position? This is the arrangement in which the neat separation described above can collapse, and it deserves specific professional advice rather than a general rule.
The instruction
Get the split in writing before you pay anything beyond a token: what is consideration for land, what is consideration for services, and what tax attaches to each. A developer who cannot produce that breakdown on request has told you something useful about the file you are about to enter.
This piece is orientation, not tax advice. GST law is amended frequently, clarifications are issued and revisited, and positions that look settled get litigated. Take the specific facts of your transaction to a chartered accountant before relying on any of it, and if you want us to walk a cost sheet through with you line by line, start the conversation.