Kokapet Was Priced at Auction. Shankarpally Still Is Not.
Government parcels in Kokapet's Neopolis blocks were sold by public auction, and the bids reset what developers believed West Hyderabad ground could cost. Shankarpally's land is still priced by the square yard, across a table.
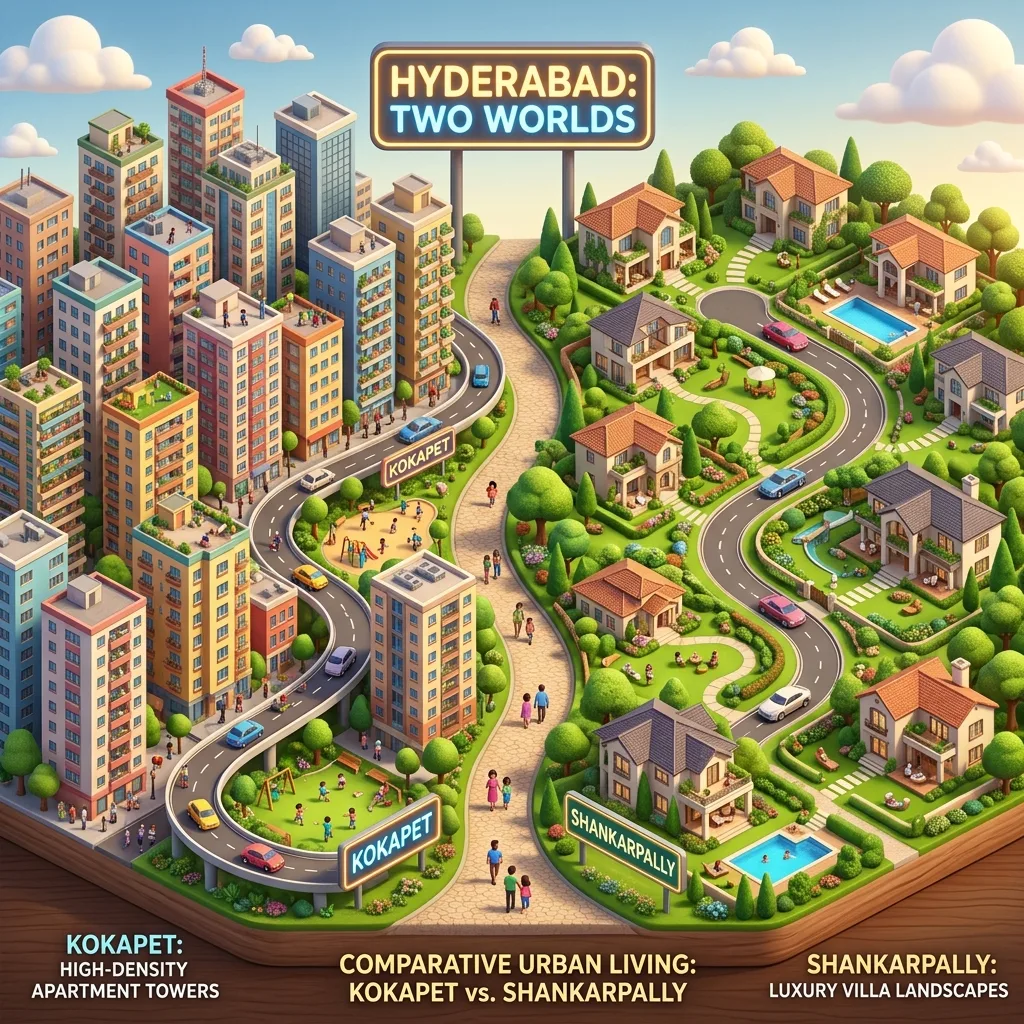
Kokapet's land was priced at auction. Government parcels in the Neopolis blocks went under the hammer, the bids became public knowledge, and developers recalibrated what they believed West Hyderabad ground could command.
Shankarpally's land is still priced by the square yard, across a table, to individual families.
That single procedural difference explains most of what follows. Two markets, both west of Hyderabad, both served by the Outer Ring Road, discovering price by entirely different mechanisms — and therefore selling entirely different things.
We should say plainly where we stand. Next Edge Realty develops plotted communities in Shankarpally, not towers in Kokapet. What follows is our attempt to argue the other side better than a partisan would.
The two purchases are not the same instrument
"Buying in Kokapet" and "buying in Shankarpally" sound parallel. The underlying assets diverge completely.
In Kokapet, the realistic purchase for a private buyer is an apartment — usually high in a tower, usually under construction. In Shankarpally, the realistic purchase is registered land: an HMDA or DTCP-approved plot with your name on the title and nothing above it but sky.
That difference cascades through everything. How the asset appreciates. What it costs to hold. How it is taxed. How it is sold. What can go wrong.
A tower flat is a claim on a developer's execution and a building's future upkeep. A plot is a claim on the land itself. Neither claim is superior in the abstract. They reward different circumstances.
What Kokapet genuinely offers
Give the established market its due.
Employment proximity no outer corridor can match. For a couple both working in the Financial District, the commute arithmetic is decisive and no amount of corridor optimism changes it.
Institutional quality. The scale of capital deployed there attracts the city's most capable developers, and construction and amenity standards reflect that.
Income from possession day. An apartment near dense employment can be let immediately. Raw land cannot.
And liquidity of a specific kind — a large active market of comparable units with visible pricing, where a seller does not have to explain the address to anybody.
If your priorities are a short commute, immediate use or rental income, and you are comfortable with apartment economics, Kokapet is a rational choice. Nothing here should persuade a Kokapet-suited buyer otherwise.
What Kokapet quietly costs
The costs are structural rather than scandalous.
Auction-derived land values must be recovered through the product, which means buyers enter at pricing that already contains an optimistic future. Appreciation from a fully priced base is arithmetic working against you. The re-rating that early Gachibowli and Kondapur buyers enjoyed has, in Kokapet's case, largely been captured by the auction itself.
Then the instrument. An apartment depreciates as a structure even while its location appreciates. Maintenance charges compound for life. Your asset's fate is pooled with a building you do not control and cannot unilaterally repair.
And supply. Towers deliver thousands of comparable units into the same resale and rental market on similar timelines, and comparability is the enemy of pricing power.
None of this makes Kokapet a mistake. It makes it a mature, efficient market — and efficient markets pay market returns rather than discovery returns.
Shankarpally is the ground-level alternative, with the obvious catch
Travel twenty-odd minutes further west and the proposition inverts. Shankarpally, roughly forty-five minutes from the Financial District, is a corridor where an individual buyer can still do what institutions did in Kokapet: own land outright, early, in the path of the city's growth.
The fundamentals are unusually solid for a frontier. A working railway station on the Hyderabad–Vikarabad suburban line links the town towards the city — an asset almost no plotted corridor in Hyderabad possesses. ORR Exit 3 on the Patancheru side connects it to the ring geometry. IIT Hyderabad at Kandi, about twenty-five minutes away, anchors an academic economy. The proposed Regional Ring Road, its northern arc approved as NH-161AA, sketches a future in which today's periphery becomes tomorrow's mid-ring.
We treat the ring as optionality rather than promise. But options acquired cheaply are the essence of frontier buying.
At Sanctuary, our 45-acre HMDA-approved community at Julkal, plots of 200 to 750 square yards start from ₹45 lakh, with a 25,000 sq. ft. clubhouse, underground utilities and Vaastu-compliant planning in place and ready for construction. Raghunath County offers DTCP-approved plots fronting the 100-ft Shankarpally–Mehtabkhan Guda–Mominpet road.
The catch is not hidden. Distance is real: the daily commute to the Financial District is a genuine cost for working households, softened but not erased by rail. Income is deferred, because land pays nothing until you build or sell. And the amenity layer is still accumulating — the retail, healthcare and dining fabric of a settled suburb remains some years out, a point we treat candidly in our Shankarpally versus Mokila comparison.
Frontier corridors also carry execution risk in aggregate. Not every layout in a rising corridor is well approved, well built or well titled. That is precisely why approval status and independent title verification matter more out here than anywhere in the settled city.
Same money, different instruments
Here is the comparison at its starkest.
A given budget in Kokapet buys a compact apartment in a tower: a finished product in a finished market. The same budget in Shankarpally buys a substantial plot, potentially with room to spare: an unfinished product in an unfinished market.
The Kokapet purchase optimises for the present — use it, rent it, live near work. The Shankarpally purchase optimises for the future — hold land through the corridor's maturation and build on your own terms.
Asking which is better is like asking whether salary is better than equity. It depends entirely on what you need the money to do, and when.
The risks are different in kind, not merely in size
Kokapet's risks are market risks: entering at a fully priced base, supply concentration in comparable units, and the long-term economics of high-rise upkeep. Its regulatory and title risks are comparatively low, because institutional development tends to arrive well papered.
Shankarpally's risks are execution and patience risks: the corridor maturing slower than hoped, the RRR timeline stretching, amenities lagging, and — for careless buyers — layouts without proper approvals. Its market risk at entry is lower precisely because less optimism is priced in.
Choose the risk you understand and can carry, not the one a salesperson minimises. Our investment overview sets out how we assess corridor risk in more detail.
A decade in two ledgers
Walk both purchases forward ten years and keep honest books.
The Kokapet ledger: an apartment bought under construction, typically financed, carrying EMIs from early in the term. Rental income beginning at possession and rising modestly. Maintenance charges and sinking-fund contributions throughout. The structure ageing into its second decade just as newer towers open nearby with fresher specifications. The asset has worked for its keep — and paid for the privilege.
The Shankarpally ledger: a plot bought outright or with a land loan. Negligible outgoings beyond property tax and community maintenance. No income at all. The corridor around it thickening year by year, with the option to build exercised whenever the household is ready, at that decade's specification rather than this one's.
Neither ledger dominates on paper. The first suits those who need the asset to participate in the family's cash flow. The second suits those who want it compounding quietly off the payroll. What ruins either is importing the other's expectations — a plot resented for paying no rent, or a flat resented for never becoming land.
Construction freedom is a feature only if you use it
Plot ownership buys total design authority: your architect, your Vaastu preferences, your room sizes, your build timeline, your budget phased to your circumstances. In a market where families increasingly want multigenerational layouts, home offices and courtyards, that authority has real value, and it is exactly what tower living cannot sell at any price.
The candid reverse: self-building is a project with a project's demands. Contractor selection, quality supervision, municipal permissions through TS-bPASS, service connections. These consume attention even when they go well, and they go well less often than owners expect.
Households with no appetite for any of it should budget for professional project management or admit that a finished product suits them better.
The two purchases are financed on different terms
Buyers rarely check this until late, and it moves the arithmetic more than most brochure differences.
A home loan against an apartment is the most standardised product in Indian retail lending: long tenures, competitive rates, and a lender comfortable with the collateral because thousands of comparable units exist.
A plot loan is a different instrument. Tenures tend to be shorter, the funded proportion of the purchase is usually lower, and lenders are considerably fussier about which layouts they will finance at all. That fussiness is not an obstacle so much as a filter — banks strongly prefer HMDA and DTCP approved layouts, which happens to be the same rule a careful buyer would apply unaided.
Composite plot-plus-construction loans exist for buyers who intend to build within a defined window, and they change the picture again, because the construction portion is drawn down in stages against progress.
The consequence for a household comparing the two markets: a given budget in Kokapet is usually a leveraged budget, while the same budget in Shankarpally is more often equity-heavy. That is not automatically worse. Less borrowing means less fragility through a soft year, but it also means more of your own capital committed to an asset that pays nothing while held.
Tax treatment differs too, and in ways worth asking an accountant about rather than an article. Interest and principal on a self-occupied home have their own reliefs. A vacant plot generally does not attract the same treatment, and capital gains rules differ by holding period and by what you do with the proceeds. Get the current position in writing before you structure either purchase.
Liquidity means two different things here
Both markets will describe themselves as liquid. The mechanics differ instructively.
Kokapet's liquidity is that of a deep order book in near-identical stock. Pricing is visible and exits are quick — but you sell in permanent competition with every comparable unit in your tower, the towers beside it, and the developer's unsold inventory, all discovered by the same buyer on the same portal.
A plot's liquidity is that of a unique asset. No two parcels share a corner, an orientation and a road, so pricing is discovered by negotiation and sales take longer. But you are never undercut by an identical unit two floors down. In rising corridors that uniqueness works for the seller. In stagnant ones it widens spreads.
Decide which failure mode you would rather manage in a hurry. That, rather than the brochure, is what liquidity means.
Who should choose which
Choose Kokapet if you work in the Financial District and prize commute above all; if you need rental income immediately; if you prefer finished, managed products; and if you accept market-rate appreciation from a fully priced base.
Choose Shankarpally if your horizon is five to ten years; if you want to own land rather than a share of a structure; if entry price and plot size matter; and if you can watch a corridor grow up around your asset without losing patience.
The most thoughtful buyers in Hyderabad frequently refuse the either-or. A household anchored by an apartment near work holds a plot further west as its long-duration asset, and the two hedge each other's weaknesses. We would say that, since we sell one half of the pair. The logic stands independent of the seller.
Whatever you decide, verify title, approvals and permissions through your own advocate — that responsibility is always the buyer's — and remember that property values move with market conditions in skylines and frontiers alike. Then go and look: a site visit that starts under Kokapet's cranes and ends on Shankarpally's open ground teaches more in one morning than a month of portal-browsing.